A Compliance Failure Years in the Making
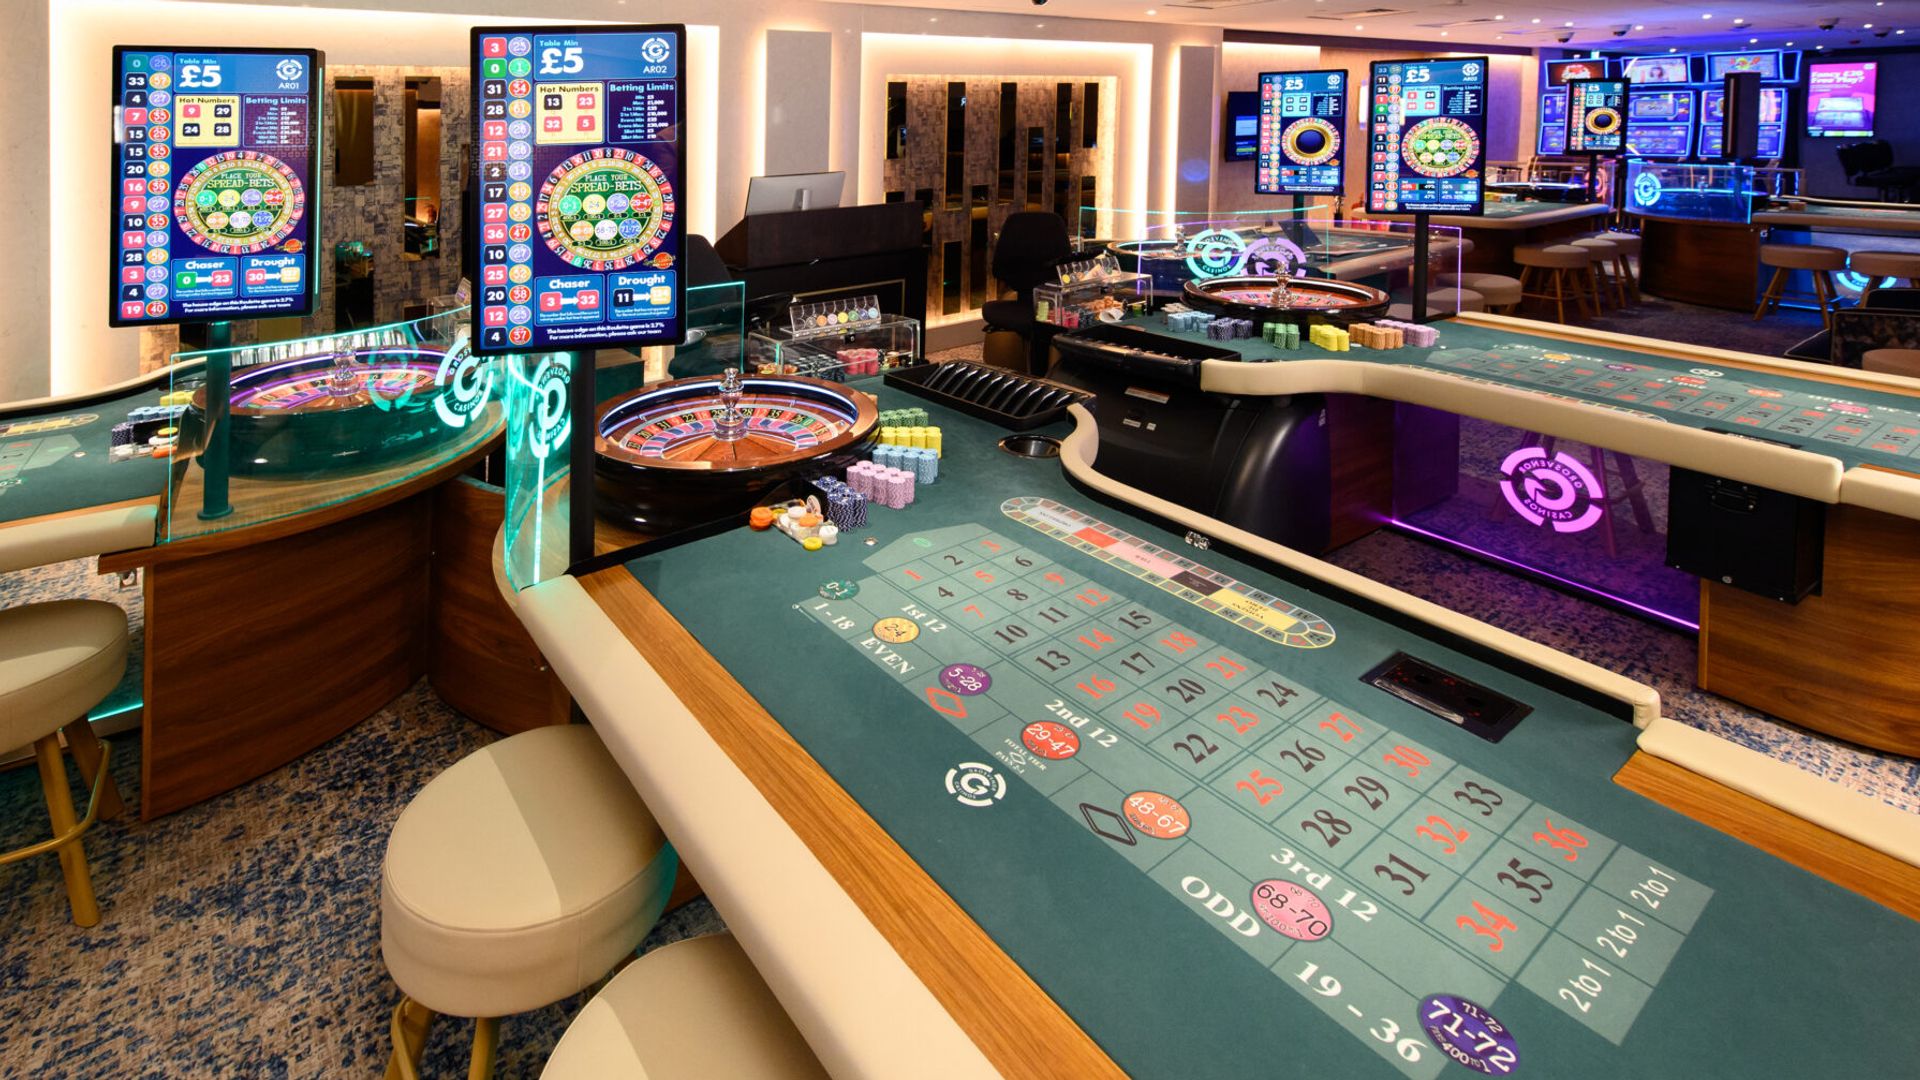
The Gambling Commission’s £5 million settlement with three subsidiaries of Rank Group PLC — Grosvenor Casinos Limited, Grosvenor Casinos (GC) Limited, and Gaming Group Limited — is not simply a regulatory fine. It is a documented record of institutional negligence: policies left unreformed for years, high-risk customers waved through without scrutiny, and vulnerable gamblers left without a single recorded intervention as they lost tens of thousands of pounds. Taken together, the failures identified across Rank Group’s 51 British casinos between 2024 and 2025 reveal an operator that allowed compliance to atrophy at precisely the points where the law, and basic duty of care, demanded vigilance.
The central thesis is straightforward: what the Commission uncovered at Grosvenor Casinos is not a series of isolated administrative oversights but the predictable consequence of structural under-investment in compliance — and the £5 million penalty, while significant in nominal terms, does not necessarily resolve the underlying accountability deficit that made those failures possible in the first place.
Anti-Money Laundering: Outdated Policies and Inconsistent Enforcement
The anti-money laundering failures documented by the Commission are striking in their specificity. Grosvenor’s operators had not updated their AML policies to reflect amendments to the Money Laundering Regulations that came into force in 2020 — a gap of at least four years during which the regulatory framework governing their obligations had materially changed while their internal procedures had not. That a group operating 51 licensed venues across Britain could allow such a foundational document to go unreformed for so long is difficult to attribute to accident; it points instead to a compliance function that lacked either the resources or the institutional priority to keep pace with its legal environment.
The consequences of that stagnation were concrete. The Commission found that AML policies, procedures and controls permitted inconsistent decisions to be applied to customers identified as carrying elevated money laundering risk — meaning that the same red flags could, depending on the venue or the staff member involved, trigger scrutiny or be quietly set aside. Enhanced customer due diligence checks, which the operators’ own internal policies required in specified circumstances, were not carried out in cases where those circumstances plainly applied. High-risk sources of funds were accepted without appropriate examination. One case documented in the Commission’s findings involved a customer who recycled approximately £85,000 in cash through a single venue over roughly eleven weeks — a pattern that, under any credible AML framework, should have prompted immediate and sustained investigation. That it apparently did not speaks to the depth of the procedural failure.
Social Responsibility: Absent Interactions, Absent Records
The social responsibility failures identified by the Commission are, in some respects, even more troubling, because they concern obligations owed directly to individuals rather than to the integrity of the financial system. In one documented case, a customer lost £50,000 during a period in which no safer gambling interaction of any kind was recorded. In another, a customer won approximately £260,000 in a short period and then lost around £250,000 within twelve days — a swing of that magnitude, at that velocity, is precisely the kind of behavioural signal that safer gambling frameworks exist to detect and respond to. No record of any interaction with that customer was kept.
The absence of records is itself a regulatory failure, but it may also obscure a more troubling possibility: that interactions did not occur at all. Regulatory frameworks governing land-based gambling in Britain require operators to identify customers displaying signs of harm and to intervene in a meaningful, documented way. The Commission’s findings suggest that Grosvenor’s systems — whether through inadequate training, poor monitoring infrastructure, or simple institutional indifference — were not reliably producing those interventions. Sue Young, the Commission’s executive director of operations, noted that the risks of anti-money laundering and social responsibility failures are “equally alive in the land-based sector,” a remark that reads as a pointed correction to an industry tendency to treat such problems as primarily an online phenomenon.
The Settlement and What It Does Not Resolve
The £5 million payment will be directed in full to the UK government’s Consolidated Fund rather than retained by the Commission, a standard feature of such settlements that ensures the regulator cannot be seen to benefit financially from enforcement action. Alongside the financial penalty, Grosvenor Casinos will be required to undergo a third-party audit to verify that it is effectively implementing AML and safer gambling policies going forward — a measure that introduces external accountability where internal accountability demonstrably failed. Whether that audit will be sufficiently rigorous, and whether its findings will be made public, remains to be seen.
It is worth noting that the settlement came as no surprise to Rank Group itself. The company disclosed in July 2025, during its second-quarter reporting, that it had proposed a £5 million payment to the Commission over what it described as “historical compliance failures,” and noted at the time that the regulator was “minded to accept” the proposal. A £5 million provision had already been entered into Rank’s 2025/26 accounts. The orderly, pre-announced nature of the settlement raises a legitimate question about whether the penalty functions as a genuine deterrent or as a manageable cost of doing business — a question that the Commission’s own enforcement rhetoric does not fully answer. That Rank Group is simultaneously campaigning against a proposed increase in the tax rate on gaming machines adds a layer of context that is difficult to ignore: a company seeking regulatory relief in one domain while absorbing a regulatory penalty in another.
The deeper implication of the Commission’s findings is that compliance failures of this kind do not emerge overnight. Policies go unreformed; monitoring systems go untested; customers displaying obvious signs of harm or suspicious financial behaviour pass through venues without meaningful scrutiny. Each of those failures represents a choice — or, more precisely, the cumulative effect of many smaller choices not to invest, not to update, not to intervene. The £5 million settlement establishes that those choices carry a price. Whether it establishes that the price is high enough to change the underlying calculus is a question that future enforcement action will have to answer.